In July, Haventree Bank, a Schedule 1 bank with decades of experience in alternative lending, launched its digital bank. It’s the first time the bank went directly to consumers, allowing them to access growth accounts and a GIC.
Rather than using a white-label solution, Haventree Bank decided to build their solution from the ground up: owning its core platform, its payments infrastructure, and the data layer behind the customer experience. It allows the bank to control how its products work, bring new features to market faster, and adapt as it learns from customers.
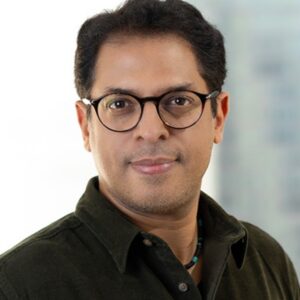
In this Q+A, Haventree’s Chief Product and Innovation Officer Salil Vijay shares why they decided to build the platform themselves, how owning their technology gives them an edge as a new bank and how it aligns with the way and where they see the bank going next.
Why build your own platform instead of licensing one? What did building in-house allow you to do that a licensed platform wouldn’t have?
SV: When we started, we looked at both options extensively. We chose to buy where the functionality is not a major differentiator and build where there’s more opportunity to innovate, which is really in the client experience. We wanted to be able to take client feedback and have full control over how we improve usability and product features.
If we used a third-party platform, we would essentially be renting out our roadmap because we’d be constrained by their features and capabilities. We wanted to fully own the innovation roadmap and differentiation of our product and client experience.
Building our own platform was necessary for both flexibility and cost from a long-term perspective, as well as ownership of intellectual property. You give up initial speed-to-market convenience, but over the long term, this approach helps us stay more competitive in Canada’s current financial landscape. Canadians no longer want to be tied down to one bank, and they are embracing FinTechs for products and solutions to build credit, ease of moving money between FIs , easy onboarding, household spend management, family banking and getting kids used to managing money early. With that in mind, we need full ownership over our platform so we can truly personalize the experience for clients and pivot quickly with consumer expectations. .
A lot of the experiences we build rely on partnership with top-class technology vendors across the world, and with the speed of evolution in the fintech space, the engineering flexibility to integrate with these vendors was another major factor.
Most off-the-shelf digital banking platforms are built for scale across many FIs without much differentiation. It’s hard to build unique experiences without impacting the unit economics.
We are building internal expertise and engineering muscle to create an innovation engine that will fuel Haventree Bank’s growth for years to come.
How did you build and test something this critical without disrupting the existing lending business?
SV: Protecting our mortgage business was non-negotiable, so we had to transform the bank while it was still running.
We approached the transformation in phases. Rather than replacing everything at once, we built a modern architecture and introduced new capabilities incrementally. We launched deposits and digital banking first on a new architecture, while allowing existing systems and processes to continue operating. We invested heavily in testing, controlled pilots, employee and friends-and-family programs, and staged rollouts before broad customer availability.
We also built cross-functional governance into the program. Product, technology, operations, risk, compliance, and customer support worked together throughout the process to validate readiness and ensure that every release met our standards before it reached customers. We’re about to launch registered products and remote deposit capture, following exactly that model.
The result was that we could continue serving our lending customers while simultaneously building the foundation for the next generation of Haventree Bank.
Now that the platform is live and owned in-house, how does that change what Haventree can build, and how quickly?
SV: The biggest advantage of our platform and architecture is that it allows us to shift from project-based delivery to continuous innovation. For example, our onboarding experience for the digital bank was initially designed for clients looking for deposit accounts, but we needed to evolve the design to accommodate our mortgage clients when we were ready. We were able to prioritize and make that change relatively painlessly because we had the flexibility of our own architecture.
Not having to rely on a vendor’s development cycles and negotiating priorities means our speed of experimentation is fast. We launch quickly, gather feedback and iterate fast based on client feedback. We can identify customer pain points, prioritize improvements, release enhancements, and measure outcomes much more rapidly than traditional banking models allow.
Most digital banks are fintechs trying to become banks. You’ve said that Haventree is a bank building like a fintech; can you talk about that approach?
SV: I am a true fan of what fintechs bring to the Canadian banking space. A lot of innovations we see today are because of fintechs raising the client experience bar; clients are now expecting their traditional banks to have the same experience. However, fintechs can run into the challenge of starting with great user experience, and then spend years building regulatory expertise, risk management capabilities and client trust. We’re approaching from the opposite direction as a federally regulated Schedule 1 bank, so we have deep expertise in risk management, compliance, lending, and serving Canadians. What we’ve done is combine that foundation with a fintech mindset around customer experience, speed, experimentation, and innovation.
The point is that Canadians shouldn’t have to choose between the security of a regulated bank and the experience of a fintech. That’s the gap we’re building for.
Any thoughts on overall strategy + approach in continuing to build and develop your in-house platform?
SV: We launched our digital bank in July this year. That was the starting line! This is a living product with continuous evolution. We have the foundational products with some of the best GIC rates on the market. Now we start expanding our product portfolio based on our research, client feedback and our strategic priorities, solving for the saving, borrowing and spending needs of our clients.
We are also working in parallel now to modernize our mortgage loan origination ecosystem on our new core and a new origination system, along with digital banking for our mortgage clients
Our philosophy is simple: build the foundational capabilities once, then continuously improve the experience layer based on customer feedback and business opportunity.
The advantage of owning the platform is that we’re not constrained by what exists today. As customer expectations evolve, so can we. Whether that’s AI-driven experiences, new payment capabilities, enhanced personalization, or products that don’t even exist yet, we now have the foundation necessary to adapt quickly.
We’ve built a platform designed not just for the products we have today, but for the products we’ll want to launch over the next decade.
Leave a Reply